Best SIPP App UK: 2 Charge No Platform Fee, 4 Don't
Freetrade and InvestEngine charge no SIPP platform fee. What Vanguard, AJ Bell, Moneybox and PensionBee cost on a £20k, £50k and £150k pot, and who wins.
The best SIPP app for most people is the one whose fee stays small as the pot grows, and whose withdrawal options still work when you reach 55. Two UK apps now charge no platform fee on a self-invested personal pension at all: Freetrade and InvestEngine. Four others are worth comparing because they do things the free pair do not: Vanguard, AJ Bell, Moneybox and PensionBee.
The gap matters more in a pension than anywhere else. A fee of 0.45% a year looks trivial on £5,000. On a pot that grows to £150,000 over a working life, a percentage fee keeps growing with it, every single year, while a flat or zero fee does not.
All fees below were checked on each provider’s own pricing pages in October 2026. They change, so confirm the current figure in the app before you transfer anything.
The two apps with no SIPP platform fee
Freetrade: free SIPP on every plan, lump sums only
Since January 2026 the SIPP has been included on all Freetrade plans, including the free Basic plan. There is no account fee and no dealing commission. What you do pay is a foreign exchange fee when you buy shares priced in another currency: 0.99% on Basic, 0.59% on Standard and 0.39% on Plus. If your pension mostly holds sterling-priced ETFs and UK shares, that fee rarely bites.
The catch is at the other end. Freetrade’s SIPP page says it currently offers only one way to take money out: an uncrystallised funds pension lump sum (UFPLS), where each withdrawal is part tax-free and part taxed. It does not offer flexi-access drawdown, and each UFPLS withdrawal costs £240. That is fine for building a pot in your 20s, 30s and 40s; it is a reason to plan a transfer to a drawdown provider before you start drawing an income.
Freetrade also warns that a pension transferred in may lose a protected pension age, which would mean waiting until 57. Our Freetrade review covers the paid plans and the FX fee in more detail.
InvestEngine: free DIY ETF pension, a manual exit
InvestEngine charges nothing for its SIPP if you pick your own ETFs, and nothing to trade or convert currency. You still pay each ETF’s own running cost. If you would rather it chose the funds for you, its Managed Portfolios carry a 0.25% annual fee. You can open the SIPP with £100, and it accepts transfers from most major pension providers.
Two limits to know. It is ETF-only, so there are no individual shares or traditional unit trusts. And its help centre describes the SIPP as built for people still saving: there is no self-service drawdown, and withdrawal requests go through its support team by email and forms. Buy for the growth years, not for retirement income.
The four that charge, and what you get for it
Vanguard: flat £4 a month on small pots, drawdown included
Vanguard’s Personal Pension costs £4 a month (£48 a year) while your balance is under £32,000, then 0.15% a year, capped at £375 across all your Vanguard accounts. Fund costs come on top, and you can only hold Vanguard’s own funds and ETFs. In return you get a pension that runs all the way through retirement: Vanguard’s self-managed service supports drawdown and says it charges no extra fee when you start taking money out.
AJ Bell: cheap for shares and ETFs, pricier for funds
AJ Bell’s SIPP charges 0.25% a year on funds up to £250,000, 0.10% from £250,000 to £500,000 and nothing above that. On shares, ETFs and investment trusts the same 0.25% is capped at £10 a month, which is what makes it good value for an ETF investor with a large pot. Dealing costs £5 a share deal (£3.50 if you made 10 or more the previous month) and £1.50 a fund deal, but regular monthly investing is free. AJ Bell says it does not charge to move your pension into drawdown or to take withdrawals.
Moneybox: cheap if you use its own funds
Moneybox’s pension has two prices. On Moneybox’s own funds the service fee is 0.15% a year, capped at £150 a year, plus a fund fee of 0.29%. On any other fund it is 0.45% a year on the first £100,000 and 0.15% above that, and that is where the costs climb. Its pension finder is also one of the easier ways to track down old workplace pots. Our Moneybox review looks at the rest of the app.
PensionBee: one all-in fee, not really self-invested
PensionBee is a personal pension rather than a true SIPP: you pick one of its ready-made plans rather than choosing individual investments. The annual fee runs from 0.50% (Tracker and Preserve plans) to 0.95%, with the default Global Leaders plan at 0.70%. The fee is halved on the part of your savings above £100,000, and it includes the fund costs, so there is nothing hidden on top. You pay more than on any of the apps above, and in exchange it does the finding, combining and drawdown for you in one simple app.
What each one costs on a £20k, £50k and £150k pot
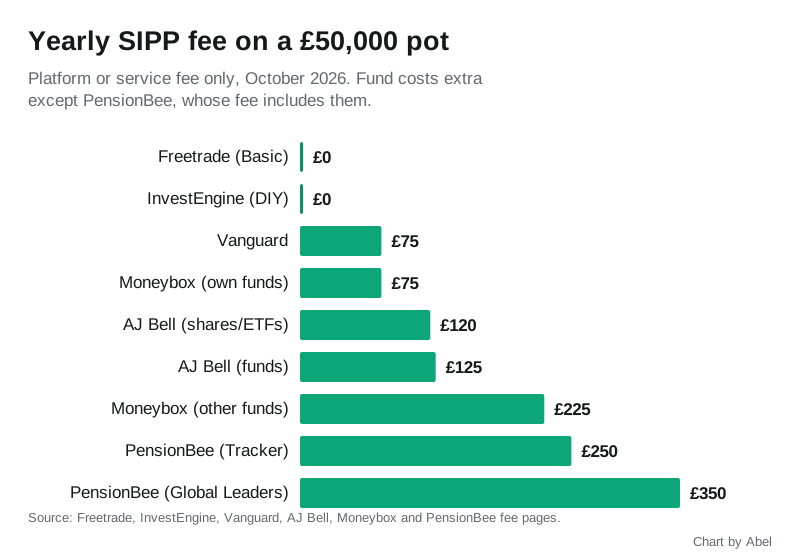
Platform or service fee only, per year. Fund and ETF running costs are extra everywhere except PensionBee, whose fee includes them.
| App | £20,000 pot | £50,000 pot | £150,000 pot |
|---|---|---|---|
| Freetrade (Basic) | £0 | £0 | £0 |
| InvestEngine (DIY) | £0 | £0 | £0 |
| InvestEngine (Managed, 0.25%) | £50 | £125 | £375 |
| Vanguard | £48 | £75 | £225 |
| AJ Bell (shares and ETFs) | £50 | £120 | £120 |
| AJ Bell (funds) | £50 | £125 | £375 |
| Moneybox (own funds) | £30 | £75 | £150 |
| Moneybox (other funds) | £90 | £225 | £525 |
| PensionBee (Tracker, 0.50%) | £100 | £250 | £625 |
| PensionBee (Global Leaders, 0.70%) | £140 | £350 | £875 |
Workings: AJ Bell’s share charge hits its £120 annual cap at £48,000. Moneybox’s other-funds figure at £150,000 is 0.45% of £100,000 plus 0.15% of £50,000. PensionBee’s is the full rate on the first £100,000 plus half the rate on the rest.
Which SIPP app suits which saver
| If you are | Look at | Why |
|---|---|---|
| Building a pot of ETFs, years from 55 | Freetrade or InvestEngine | No platform fee at any size |
| Holding UK and US shares in a pension | Freetrade | Individual shares, no account fee; watch the FX fee |
| Near retirement and want drawdown | Vanguard or AJ Bell | Both support drawdown with no withdrawal fee |
| A large ETF pot that you trade rarely | AJ Bell | Share charge capped at £120 a year |
| Wanting someone else to pick the funds | Moneybox (own funds) or InvestEngine Managed | Lowest ready-made options here |
| Wanting old pensions found and combined for you | PensionBee or Moneybox | The simplest consolidation; you pay for it |
A sensible split for a lot of savers is a free app while the pot grows, then a transfer to a drawdown provider in your early 50s. Transfers between SIPPs are normally free to receive, but check the leaving provider’s exit terms.
Check these before you transfer an old pension
- Guarantees. Old workplace and personal pensions can carry a guaranteed annuity rate, a protected tax-free cash amount or a protected pension age. Moving can lose them. Get the scheme’s details in writing first.
- Defined benefit (final salary) schemes. These are not like the others. If the transfer value is over £30,000 you must take regulated financial advice before moving.
- Out of the market. Some transfers sell your investments and move cash, so you sit out for a week or more. InvestEngine warns of this on its transfer page.
- Tax relief. A SIPP adds basic-rate relief automatically: pay in £80 and the provider claims £20 from HMRC. Higher and additional-rate taxpayers claim the rest through Self Assessment. GOV.UK sets out how pension tax relief works.
If you have lost track of old pots, start with our guide to tracking pensions in one app before you choose where to put them.
Frequently asked questions
What is the cheapest SIPP app in the UK? On platform fees, Freetrade and InvestEngine are joint cheapest at £0 for a self-invested pension. Freetrade suits share investors who can live with its FX fee; InvestEngine suits ETF investors. Both are weaker at the withdrawal stage.
Is a SIPP app safe? Your investments are held in a ring-fenced account, separate from the app’s own money. If a provider fails, eligible claims for losses caused by its failure are covered by the FSCS, normally up to £85,000 for investment business. That does not protect you from investments falling in value.
Can I have more than one SIPP? Yes. You can hold several pensions and pay into more than one in the same tax year, as long as your total contributions stay within your annual allowance.
When can I take money out of a SIPP? From 55, rising to 57 from 6 April 2028, unless you have a protected pension age. Usually 25% can come out tax-free and the rest is taxed as income.
Does Freetrade offer pension drawdown? Not at the moment. Freetrade’s SIPP page says it only offers UFPLS lump sums, at £240 per withdrawal. If you want a regular income from your pension, plan to move to a provider with flexi-access drawdown such as Vanguard or AJ Bell.
Is PensionBee a SIPP? Not in the usual sense. It is a personal pension with a menu of managed plans, so you cannot pick individual shares or ETFs. Its fee includes the fund costs, which makes it simple but dearer than a DIY SIPP.