Best Junior ISA App UK: 3 Charge No Platform Fee
Freetrade, HL and Fidelity charge no Junior ISA platform fee. What Vanguard, AJ Bell and Moneybox cost on £20,000, plus the £9,000 rules.
The best Junior ISA app for most families is one that charges no platform fee, lets grandparents pay in, and holds cheap global index funds or ETFs. Three UK providers now charge nothing to hold a stocks and shares Junior ISA: Freetrade, Hargreaves Lansdown and Fidelity. Vanguard, AJ Bell and Moneybox charge a percentage, and each has a reason you might still pick it.
A Junior ISA runs for up to 18 years, longer than most adult ISAs are ever held, so the fee compounds for a long time. On a child’s account that reaches £20,000, a 0.25% fee costs £50 a year; a zero fee costs nothing, however big the pot gets.
One app people expect to see here is missing: InvestEngine does not offer a Junior ISA. Its help centre, updated on 30 October 2026, says it does not currently offer Cash ISAs, Lifetime ISAs or Junior ISAs. Several comparison sites still list one.
All fees below were checked on each provider’s own pages on 31 October 2026. Confirm them in the app before you open or transfer anything.
The Junior ISA rules that apply in every app
These come from GOV.UK’s Junior ISA page and are the same wherever you open the account:
- Allowance: £9,000 per child in the 2026 to 2027 tax year, shared across a cash Junior ISA and a stocks and shares Junior ISA if the child has both.
- Who opens it: a parent or guardian with parental responsibility, for a child under 18 living in the UK. Anyone (grandparents, godparents) can then pay in, but the money becomes the child’s.
- At 16: the child can take control of the account, but cannot withdraw.
- At 18: the money is theirs to withdraw or keep invested; the account turns into an adult ISA.
- Child Trust Fund: a child cannot hold a Junior ISA and a Child Trust Fund at the same time. Ask the Junior ISA provider to transfer the trust fund in.
The allowance runs per tax year, to 5 April. Any part you do not use is lost; it does not roll over.
The three with no platform fee
Freetrade: £0 on every plan, from £1
Freetrade’s Junior ISA is included on all its plans, including the free Basic plan, with no account fee and no dealing commission. You can top it up with as little as £1, and it can hold shares, funds, ETFs, investment trusts and UK Treasury bills, over 8,700 choices in all.
The cost to watch is foreign exchange. Buying a share priced in dollars or euros carries an FX fee of 0.99% on Basic, 0.59% on Standard and 0.39% on Plus. For a child’s account built on a sterling-priced global tracker ETF, that rarely applies. If you want to pick US shares for them, it adds up. Our Freetrade review covers the plans in more detail.
Hargreaves Lansdown: £0 account charge, £0 online dealing
Hargreaves Lansdown’s Junior ISA page lists a 0% annual account charge and says you will not pay online dealing charges. You can start with a £100 lump sum or £25 a month. It holds funds, shares, ETFs and investment trusts. Fund running costs still apply to whatever you buy.
Fidelity: no service fee, from £25
Fidelity says it does not charge a service fee on investments held in junior accounts, and you can start from £25. Friends and family can gift money into the account. Like HL, it is a fund supermarket first, so it suits a parent who wants an index fund or a ready-made portfolio rather than individual shares.
The three that charge, and why you might still pick one
Vanguard: 0.15%, Vanguard funds only
Vanguard charges an account fee of 0.15% a year on a Junior ISA, capped at £375. Unlike its adult ISA, there is no flat monthly minimum on small Junior ISA balances. Fund costs run from 0.06% to 0.79%. The catches: you can only hold Vanguard’s own 85-plus funds, and the minimum is higher than anywhere else at £100 a month or a one-off £500. It suits a family that already wants a LifeStrategy or global tracker fund and will not change its mind.
AJ Bell: capped for ETFs, 0.25% for funds
AJ Bell’s Junior ISA charges 0.25% a year, but on shares, ETFs and investment trusts that charge is capped at £2.50 a month, or £30 a year. On funds there is no cap. Share deals cost £5 (£3.50 if you made 10 or more the previous month) and fund deals £1.50, while regular monthly investing into selected investments is free. Hold an ETF, invest monthly, and a large AJ Bell Junior ISA costs no more than £30 a year.
Moneybox: the easiest app, the priciest on other funds
Moneybox offers only a stocks and shares Junior ISA. On Moneybox’s own funds the service fee is 0.15% a year plus a fund fee of 0.29%; on other providers’ funds the service fee is 0.45%. On top of that sits a monthly subscription, which Moneybox’s help pages put at £1, free for the first three months and waived for customers with £5,000 or more across their investing accounts. Cash waiting to be invested earns interest (2.50% AER variable when we checked). Moneybox’s help pages say new Junior ISAs are currently only available to existing Moneybox customers. Our Moneybox review covers the rest of the app.
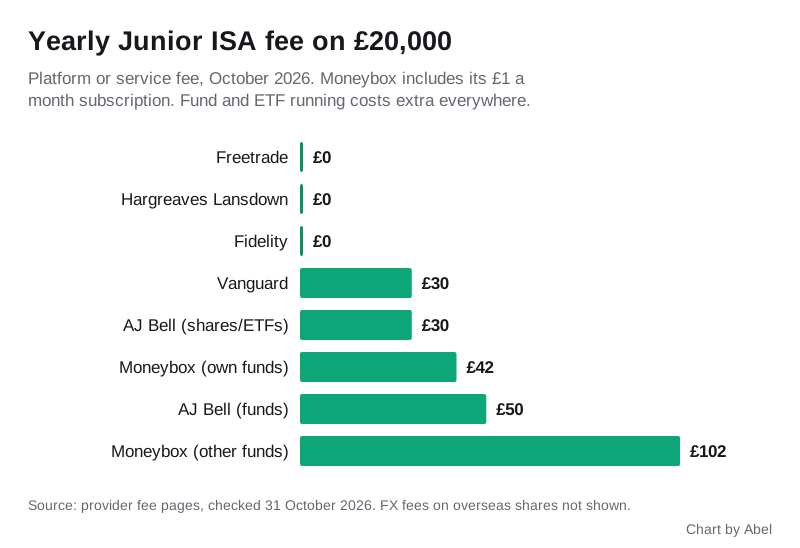
What each one costs on a £20,000 Junior ISA
Platform or service fee per year. Fund and ETF running costs are extra in every case.
| Provider | Yearly fee on £5,000 | Yearly fee on £20,000 | Minimum to start |
|---|---|---|---|
| Freetrade | £0 | £0 | £1 |
| Hargreaves Lansdown | £0 | £0 | £25 a month or £100 |
| Fidelity | £0 | £0 | £25 |
| Vanguard | £7.50 | £30 | £100 a month or £500 |
| AJ Bell (shares and ETFs) | £12.50 | £30 | Not stated |
| AJ Bell (funds) | £12.50 | £50 | Not stated |
| Moneybox (own funds, with subscription) | £19.50 | £42 | Not stated |
| Moneybox (other funds, with subscription) | £34.50 | £102 | Not stated |
The Moneybox rows include a full year of the £1 subscription; if yours is waived, take £12 off. Dealing charges and FX fees are not included.
Which one to pick
- Lowest cost with shares or ETFs: Freetrade, as long as you mostly buy sterling-priced investments.
- Lowest cost with funds and the most choice: Hargreaves Lansdown or Fidelity, both at £0.
- One fund, set and forget: Vanguard, if you can meet the £500 or £100 a month minimum.
- You already invest with AJ Bell: its capped charge on ETFs keeps a large pot cheap.
- You want round-ups and the simplest app: Moneybox, ideally on its own funds, and only if you already have a Moneybox account.
If you are saving cash rather than investing, a cash Junior ISA from a bank or building society usually pays more than these apps do on uninvested cash. Our guide to the best savings apps for children covers spending cards and children’s savings accounts, and if you want to move an existing Junior ISA, the process works the same way as in our ISA transfer walkthrough: ask the new provider to do it, and never withdraw the money yourself. For your own allowance, see the best stocks and shares ISA apps.
Frequently asked questions
What is the best Junior ISA app in the UK? On fees, Freetrade, Hargreaves Lansdown and Fidelity all charge no platform fee on a stocks and shares Junior ISA. Freetrade suits share and ETF investors and starts from £1; HL and Fidelity suit fund investors and start from £25.
Does InvestEngine have a Junior ISA? No. InvestEngine’s own help centre says it does not currently offer Junior ISAs, Lifetime ISAs or Cash ISAs, only a stocks and shares ISA, a SIPP and general accounts.
How much can I put in a Junior ISA in 2026? £9,000 per child in the 2026 to 2027 tax year, across cash and stocks and shares Junior ISAs combined. The limit applies to the child, so payments from parents, grandparents and friends all count towards the same £9,000.
Can a child have a cash Junior ISA and a stocks and shares Junior ISA? Yes. GOV.UK says a child can have one or both types, as long as total payments stay within the £9,000 allowance. Each child can only hold one of each type at a time.
What happens to a Junior ISA when the child turns 18? The money becomes theirs. They can withdraw it, or keep it invested, as the account becomes an adult ISA. They can take control of how it is managed from 16 but cannot withdraw before 18.
Can I transfer a Child Trust Fund into a Junior ISA app? Yes. A child cannot hold both, so ask the Junior ISA provider to transfer the Child Trust Fund in. It is worth checking whether the old account charges an exit fee first.
Capital at risk: investments can fall as well as rise, and your child may get back less than was paid in. This page is general information, not financial advice.