Transfer an ISA to Another Provider: The 15-Day Rule
To transfer an ISA to another provider, start the switch with the new app; never withdraw first. Time limits, partial moves and the April 2027 catch.
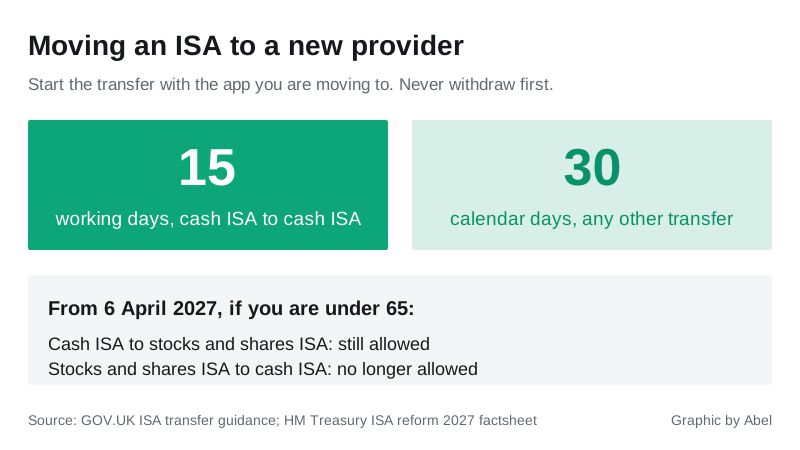
To transfer an ISA to another provider without losing the tax wrapper, you start the transfer from the new app, not the old one, and you never take the money out yourself. The new provider asks the old one for the funds, the money moves between them directly, and it stays inside an ISA the whole time. Withdraw it to your bank and pay it back in, and it counts as a fresh subscription against this year’s £20,000 allowance, so older savings lose their tax-free status for good.
That one rule causes most of the costly mistakes. The rest of this page covers the time limits, what you can move part of, the traps with flexible ISAs and Lifetime ISAs, and the rule change on 6 April 2027 that turns one type of transfer into a one-way door.
The short version
| Question | Answer |
|---|---|
| Who starts the transfer? | The provider you are moving TO |
| Cash ISA to cash ISA, maximum time | 15 working days |
| Any other ISA transfer, maximum time | 30 calendar days |
| Does it use this year’s allowance? | No, a proper transfer is not a new subscription |
| Can I move only part of it? | Yes, including money paid in this tax year (since 6 April 2024) |
| Can I move cash ISA money into an investing ISA? | Yes |
| Can I move investing ISA money into a cash ISA? | Yes until 5 April 2027; from 6 April 2027 only if you are 65 or over |
| What if I withdraw it myself first? | It stops being ISA money; paying it back in uses allowance |
The time limits come from GOV.UK’s guidance on transferring your ISA.
How to transfer an ISA between apps, step by step
- Check the new app accepts transfers in. Not every ISA does, and some accept cash ISA transfers but not stocks and shares, or the reverse. The app’s help pages or its ISA product page will say. Look for an “ISA transfer” or “move an existing ISA” option in the app.
- Open the new ISA, or use one you already have. You can usually start the transfer as part of opening the account.
- Fill in the transfer request with the new provider. You will need the old provider’s name, your old ISA account number or reference, and, for a bank cash ISA, often the sort code. Say whether you want to move all of it or a set amount.
- Choose cash or in-specie for investments. See the section below. A cash ISA is always moved as cash.
- Leave the old account alone. Do not close it and do not withdraw from it while the transfer is running. The old provider closes it or leaves the remainder in place, depending on whether you moved all or part.
- Check the money lands. Confirm the amount, and that any interest earned up to the transfer date came across too.
If the old provider is a bank and the new one is an app, the bank may send a letter or ask you to confirm. Answer it quickly; a stalled confirmation is a common reason transfers run late.
How long it should take
GOV.UK sets the maximum at 15 working days for a transfer between cash ISAs, and 30 calendar days for every other kind, which covers stocks and shares, moving cash into an investing ISA and the reverse. App to app transfers between providers that use the industry’s electronic transfer systems are often much quicker than that.
If a transfer goes past the limit, complain to the provider holding things up first. If you are not happy with the reply, take it to the Financial Ombudsman Service, which can award interest you lost while the money was stuck.
Cash transfer or in-specie?
For a stocks and shares ISA there are two ways to move it:
- Cash transfer. The old provider sells your holdings and sends the cash. It is simpler and usually quicker, but your money is out of the market while it travels, and if prices rise in that gap you buy back at a higher price. You may also pay a dealing fee to buy again.
- In-specie transfer. Your actual funds and shares are re-registered with the new provider without being sold, so you stay invested. It only works if the new app can hold the same investments. Many apps offer a narrower range than a full investment platform, so a fund you hold may not be available, and that part has to be sold.
Ask the new app which holdings it can take before you choose. Some apps only accept cash transfers in, and some old providers charge an exit fee, so check both fee pages.
Moving only part of an ISA
Since 6 April 2024 you can transfer part of the money you have paid in during the current tax year, not just part of older savings. Before then, current-year money had to move in one lump. You can now move, say, £3,000 of this year’s £8,000 to a new app and leave the rest where it is.
The same April 2024 change means you no longer need to transfer at all just to pay into a new app. You can now pay into more than one ISA of the same type in a tax year, as long as the total across all of them stays within £20,000. If all you want is a better rate on new money, open the new ISA and pay into it. Transfer only the savings you already have.
The flexible ISA trap
A flexible ISA lets you take money out and put it back in the same tax year without using fresh allowance. But the replacement has to go back into the same account. If you withdraw £2,000 from a flexible cash ISA in May, then transfer that ISA to a new app in June, putting the £2,000 into the new app counts as a new subscription.
So if you have made a withdrawal this tax year that you meant to replace, put it back before you start the transfer. HMRC’s tax-free savings newsletter of May 2024 sets out how flexible replacements and transfers interact.
Lifetime ISAs are different
A Lifetime ISA can move to another Lifetime ISA provider without any charge, within 30 calendar days. Money paid in during the current tax year has to move in full, though older payments can be split.
Moving a Lifetime ISA into a different kind of ISA is treated as a withdrawal. Unless you are 60 or over or terminally ill, the 25% withdrawal charge applies, which takes back the government bonus and some of your own money. Transfers in the other direction, from a cash or stocks and shares ISA into a Lifetime ISA, are allowed but count toward the £4,000 Lifetime ISA limit for the year. The rules are on GOV.UK’s Lifetime ISA transfer guidance. Our Lifetime ISA apps comparison shows which apps accept them.
What changes on 6 April 2027
From 6 April 2027 the cash ISA limit falls to £12,000 for savers under 65. To stop people getting round that cap, anyone under 65 will no longer be able to transfer money from a stocks and shares ISA or an Innovative Finance ISA into a cash ISA. Cash into an investing ISA stays allowed.
That makes the order of your moves matter. If you are under 65 and thinking of consolidating cash savings into an investing app, money you move after 6 April 2027 cannot come back into cash. If you want investments back in cash, that transfer has to happen by 5 April 2027. Our page on the cash ISA limit for 2027 covers the rest of the change.
Before you switch
- Compare like with like. A higher headline rate on a cash ISA can be a bonus that drops off after twelve months. Our list of best cash ISA apps notes which rates are boosted.
- Check the new provider’s protection. Cash in a UK-authorised bank’s ISA is covered by the FSCS up to £120,000 per person per banking licence. If you already hold money with another brand on the same licence, the limit is shared.
- Watch notice and fixed terms. Leaving a fixed-rate cash ISA early through a transfer usually means an interest penalty. Leaving a notice account may mean waiting out the notice.
- For investing apps, check the fee on the way out as well as in. See our stocks and shares ISA apps comparison.
If you are leaving an app entirely, our guide to closing a money app account covers what to do once the ISA has moved.
Frequently asked questions
Does transferring an ISA to another provider use my allowance? No. A transfer made through the new provider moves existing ISA money, so it is not a new subscription. Only withdrawing and paying back in uses allowance.
How long does an ISA transfer take? No more than 15 working days between cash ISAs, and no more than 30 calendar days for any other type, according to GOV.UK. Many app to app transfers finish sooner.
Can I transfer only some of my ISA? Yes. Since 6 April 2024 you can move part of the money paid in this tax year as well as part of older savings, and leave the rest with the old provider.
Can I transfer a stocks and shares ISA into a cash ISA? Until 5 April 2027, yes. From 6 April 2027, savers under 65 will not be able to move money from a stocks and shares or Innovative Finance ISA into a cash ISA.
Will I lose interest while the ISA is transferring? Cash ISA money should keep earning interest with the old provider until it leaves, and that interest moves with it. For investments transferred as cash, you are out of the market during the transfer.
What if my ISA transfer is late? Complain to the provider causing the delay. If that does not resolve it, the Financial Ombudsman Service can look at it and may order compensation for lost interest.
Sources
- GOV.UK, Individual Savings Accounts: transferring your ISA, checked 7 October 2026.
- GOV.UK, Transfer Lifetime ISAs between managers.
- HMRC, Tax-free savings newsletter 12, May 2024, on partial transfers and flexible ISAs.
- HM Treasury, ISA reform 2027 factsheet.