Monzo 1p Saving Challenge: £667.95 and About £11 Interest
The Monzo 1p Saving Challenge saves £667.95 in a year and pays 5% AER, but only about £11 interest, less than Extra's £36 fee. How it works, 2x, 4x, pauses.
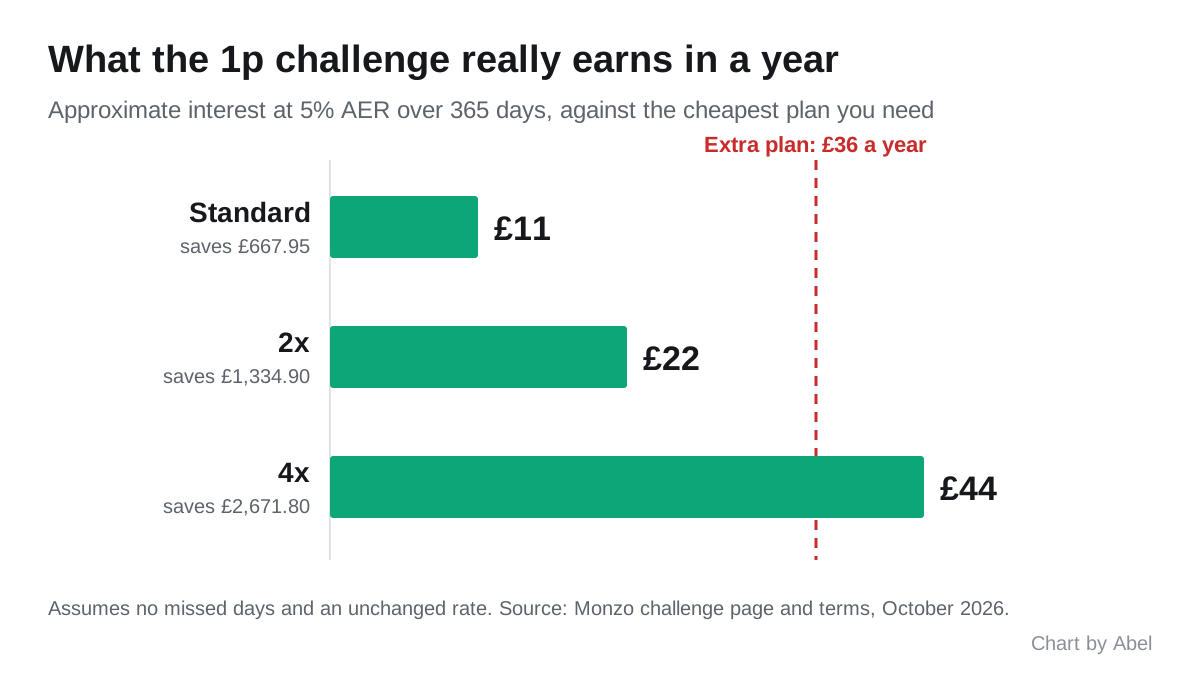
The Monzo 1p Saving Challenge moves 1p into a pot on day one, 2p on day two, 3p on day three, and keeps going until you put away £3.65 on day 365. Finish it and you have £667.95, plus interest at 5% AER (variable). That headline rate is the part people get wrong. Because the pot starts almost empty and only reaches £667.95 on the last day, the 5% is earned on an average balance of about £224, which works out at roughly £11 of interest over the whole year. You also need a paid Monzo plan to take part, and the cheapest one costs £36 a year.
None of that makes it a bad idea. It is a habit tool that happens to pay interest, not a savings account that happens to be fun. Here is how it works, what you will really earn at each level, and the rules in the terms that trip people up.
How the 1p challenge works
Each day Monzo moves money from your personal account into a Challenge Pot automatically. The amount goes up by a penny every day, so the transfer on any day is that day’s number in pence. Monzo’s 1p Saving Challenge page lists three levels, and you can switch between them at any time, with the new level starting the next day:
| Level | Day 1 | Day 365 | Total saved after 365 days |
|---|---|---|---|
| Standard (1x) | 1p | £3.65 | £667.95 |
| 2x | 2p | £7.30 | £1,334.90 |
| 4x | 4p | £14.60 | £2,671.80 |
Totals exclude interest. Some checkpoints on the standard level: £4.65 after 30 days, £168.36 at the halfway mark (day 183), and £667.95 on day 365.
The challenge runs for 365 days from whichever day you start, so you do not have to begin in January. If your year includes 29 February, there is a day 366 transfer of £3.66 and the standard total becomes £671.61, according to the challenge terms.
Who can join: you need Extra, Perks or Max
Since 1 February 2025 the Challenge Pot has been limited to customers on a paid Monzo plan, and free trials do not count. That means Extra at £3 a month, Perks at £9, Max from £19, or Max + family. You must be 18 or over (Max is limited to ages 18 to 69).
If you cancel or downgrade the plan part way through, two things happen under the current terms: interest stops, and you cannot add any more money to the challenge. Upgrade again before the year is up and you can restart it. We compare the three plans in detail in are Monzo’s paid plans worth it.
What 5% AER actually earns you
Interest is worked out daily on whatever is in the pot and paid on the first of each month. The pot grows slowly at first and fast at the end, so across the year it holds about £224 on average. At 5% AER, that is:
| Level | Average balance over the year | Interest (approx.) | Extra plan fee for the year |
|---|---|---|---|
| Standard (1x) | About £224 | About £11 | £36 |
| 2x | About £448 | About £22 | £36 |
| 4x | About £895 | About £44 | £36 |
These figures are our own sums, assuming the rate stays at 5% for the full year and you never miss a day. Monzo can cut the rate with 14 days’ notice.
Two conclusions follow. First, on the standard level the interest does not come close to paying for even the cheapest plan, so join because you already want Extra, Perks or Max for something else. Second, only the 4x level earns more than Extra costs, and only by a few pounds. For comparison, Monzo’s free Instant Access Savings pays 2.75% AER, so the same daily pattern of deposits there would earn about £6. The challenge rate is better, but the gap on a year’s run is about £5.
Missed days, pauses and catching up
The rules here are in the Savings Challenge terms (version 1.1, dated 9 January 2026), not on the feature page:
- Not enough money in your account: Monzo tries the transfer again each day for three days in a row. If the money still is not there on the third day, the challenge is paused until you restart it.
- Pausing: you can pause at any time yourself. When you restart, you choose whether to add the money for the days you missed.
- No extra deposits: you cannot pay in more than the schedule while the challenge is running. Catching up on missed days is the only way to add a lump sum, so you cannot pay the expensive final days in advance.
- Withdrawals: you can take money out at any time, and it usually lands in your personal account instantly. You can add it back later. You cannot pay anyone directly from the pot.
The expensive end of the year
The challenge is cheap for months and then it is not. The first 30 days cost £4.65 in total. The last 31 days, days 335 to 365, cost £108.50, at £3.35 to £3.65 a day. On 4x, that final month is £434.
If you start on 1 January, that final stretch lands in December, which is the month most people struggle with. Two ways round it: start the challenge in a month that leaves the last 30 days somewhere quieter (starting in March ends it in late February), or put a little aside for it in a sinking fund from the summer.
What happens on day 365
Automatic transfers stop and Monzo asks you where you want the money to go. Interest stops at the end of the challenge even if you leave the money in the pot, so do not leave it there. Once you have made your choice, the pot closes. You can start a new challenge while the current one is still running, or wait until it finishes.
The money is held by Monzo Bank and eligible deposits are covered by the FSCS up to £120,000 per person, combined with anything else you hold at Monzo.
Is it worth doing?
Yes, if the thing you are short of is the habit rather than the rate. The daily amounts are small enough that most people never notice them until the final quarter, and by then you have a few hundred pounds you would otherwise have spent. It works best as a “free” extra for someone already paying for Monzo Perks or Max.
If you are only after interest, it is not the best home for your money. A plain easy-access account with a decent rate, or a regular saver, will beat it once the plan fee is counted. Our Monzo savings pots review covers the other pots and their current rates.
Frequently asked questions
How much do you save with the Monzo 1p Saving Challenge? £667.95 over 365 days on the standard level, £1,334.90 on 2x and £2,671.80 on 4x, before interest. A year that includes 29 February adds a day 366 payment, taking the standard total to £671.61.
Is the Monzo 1p challenge free? No. Since 1 February 2025 you need a paid plan (Extra, Perks, Max or Max + family) to open a Challenge Pot, and free trials do not count. The cheapest, Extra, is £3 a month.
How much interest does the 1p challenge earn? About £11 over a full year on the standard level at 5% AER, because the average balance is only about £224. 2x earns about £22 and 4x about £44, assuming the rate does not change.
What happens if I don’t have enough money for a daily payment? Monzo retries for three days in a row. If there is still not enough on the third day, the challenge pauses until you restart it, and you can choose to catch up on the missed days when you do.
Can I take money out of the challenge pot? Yes, at any time, and it usually arrives in your personal account instantly. You can put it back later, but you cannot pay in more than the schedule allows.
Is the Monzo 1p challenge prize draw still open? No. The 2026 prize draws (one £10,000 prize and 100 monthly £100 prizes) were only open to people who started the challenge and opted in by 31 January 2026. You can still start the challenge itself on any day.