ISA Allowance 2026/27: How £20,000 Splits Across Apps
The ISA allowance for 2026/27 is £20,000, and you can split it across several apps, even two cash ISAs. The rules, the traps and what changed in October.
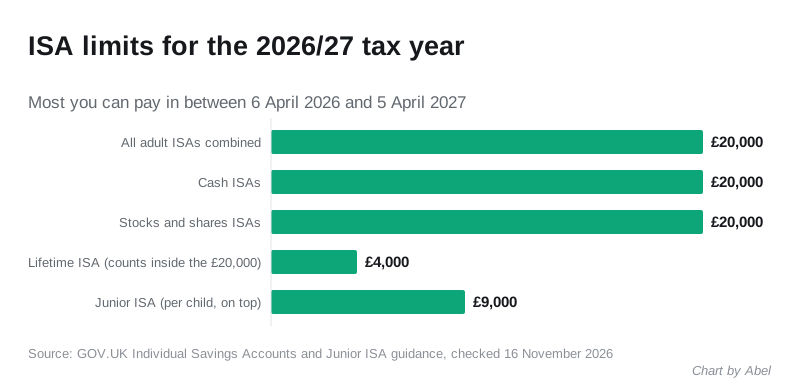
The ISA allowance for 2026/27 is £20,000. That is the most you can pay into all your adult ISAs combined between 6 April 2026 and 5 April 2027, and you can split it across as many apps as you like: a cash ISA with one, a stocks and shares ISA with another, even two cash ISAs with two different apps in the same year. What you cannot do is go over £20,000 in total, or pay into more than one Lifetime ISA in the year.
Every rule below comes from GOV.UK’s ISA guidance and HMRC’s October 2026 savings newsletter, checked on 16 November 2026.
The 2026/27 limits at a glance
| ISA | Most you can pay in for 2026/27 | Counts toward the £20,000? |
|---|---|---|
| All adult ISAs combined | £20,000 | This is the £20,000 |
| Cash ISA | £20,000 | Yes |
| Stocks and shares ISA | £20,000 | Yes |
| Innovative finance ISA | £20,000 | Yes |
| Lifetime ISA | £4,000, plus a 25% bonus of up to £1,000 | Yes, the £4,000 you pay in |
| Junior ISA | £9,000 per child | No, it is the child’s own allowance |
The government bonus on a Lifetime ISA does not use up any allowance; only the money you pay in counts. Interest, dividends and investment growth do not count either. The allowance is about what goes in, not what the account is worth.
The cash ISA cut is off
If you read that the cash ISA limit was dropping to £12,000, that plan is dead. It was announced in the November 2025 Budget for 6 April 2027, and the Budget on 28 October 2026 cancelled it. HMRC’s newsletter of 29 October says the £20,000 annual cash ISA limit “will be retained from 6 April 2027”, and the regulations that introduced the £12,000 limit will be revoked. The planned ban on moving money from a stocks and shares ISA into a cash ISA, and the 22% charge on cash held in a stocks and shares ISA, went with it.
So for 2026/27 and 2027/28 the position is the same: all £20,000 can go into cash if you want. Our page on the cash ISA limit for 2027 has the full story of what was planned and dropped.
How splitting works across apps
Since 6 April 2024 you can pay into more than one ISA of the same type in a tax year. GOV.UK gives the example of £10,000 in one cash ISA, £3,000 in another cash ISA and £7,000 in a stocks and shares ISA, all in one year. For app users that means you can:
- Keep an easy-access cash ISA with a savings app for your emergency fund and open a second cash ISA with another app when it launches a better rate, without closing the first.
- Run a stocks and shares ISA with Trading 212 for an index fund and another with Freetrade or Lightyear for individual shares.
- Open a Lifetime ISA with Moneybox and still have room for £16,000 elsewhere.
Two exceptions. You can pay into only one Lifetime ISA in a tax year, and a child can have only one cash Junior ISA and one stocks and shares Junior ISA at a time.
Nobody checks the total for you as you go. Each app knows only what you paid into it, so it is your job to keep the combined figure at or under £20,000. If you go over, HMRC finds out from the returns providers send in, and the usual outcome is that the excess subscription is removed from the ISA and any tax relief on it is taken back. Keep a running note in your budgeting app or a spreadsheet of what has gone into each ISA since 6 April.
Three worked examples
Saver with two cash ISAs. You put £6,000 into a flexible cash ISA in one app in April and £9,000 into a cash ISA in another app in August when it paid a better rate. You have used £15,000 and have £5,000 left for the rest of the tax year, in any ISA you choose.
First-time buyer. You pay £4,000 into a Lifetime ISA (the government adds £1,000), £10,000 into a stocks and shares ISA and £6,000 into a cash ISA. That is £20,000 used. The £1,000 bonus does not count toward it.
Family. You use your own £20,000 and pay £9,000 into your child’s Junior ISA. That is allowed: the Junior ISA limit belongs to the child, not to you. If grandparents also pay in, everyone’s payments to that child count toward the one £9,000 limit.
Flexible ISAs: taking money out and putting it back
A flexible ISA lets you withdraw cash and pay it back in during the same tax year without using fresh allowance. GOV.UK’s example: you pay in £10,000, then take out £3,000. With a flexible ISA you can still pay in £13,000 that year; with a non-flexible ISA only £10,000.
The catch for app users is that the replacement only works in the same ISA you took it from, and only before 5 April. Move that ISA to another provider first and the money you put back counts as new allowance. Not every app offers flexibility either: Trading 212’s cash ISA, Plum’s cash ISA and InvestEngine’s stocks and shares ISA are flexible, but J.P. Morgan Personal Investing (Nutmeg) says its stocks and shares ISA is not, as our Nutmeg review explains. Check the key facts document before you rely on it.
Transfers do not use your allowance
Moving existing ISA money from one app to another is a transfer, not a new subscription, so it does not touch your £20,000. The rule that matters: ask the new app to arrange the transfer. If you withdraw the money and pay it in yourself, it counts as a new payment and the tax-free status on that money is lost unless you have allowance left. Since April 2024 you can also transfer part of the money you paid in during the current tax year, not just all of it. Our guide to transferring an ISA between apps covers the time limits: 15 working days for cash to cash, 30 calendar days for other transfers.
What changed for 2026/27 that most pages miss
From 6 April 2026, cryptoasset exchange traded notes can no longer be bought inside a stocks and shares ISA. GOV.UK now lists them as innovative finance ISA investments; any already held in a stocks and shares ISA before that date can stay. Going the other way, long-term asset funds now belong in a stocks and shares ISA rather than an innovative finance ISA. If an app suddenly stops letting you buy a crypto ETN in your ISA, this is why.
The 28 October 2026 Budget also cut the Lifetime ISA withdrawal charge to 20% when the money buys a first home costing more than £450,000, from 29 October 2026, and confirmed a new First Time Buyer ISA from April 2029. Neither changes the £20,000 allowance. Our best Lifetime ISA apps page explains how the account works now.
Who can use the allowance
You must be 18 or over and UK resident (or a Crown servant posted abroad, or their spouse or civil partner). Since April 2024, 16 and 17 year olds can no longer open an adult cash ISA; a Junior ISA is the route for them. If you move abroad you can keep your ISAs open and tax-free, but you cannot pay in until you are UK resident again. ISAs are held in one name only, so a couple has two allowances, £40,000 a year between them, but no joint ISA.
The allowance does not roll over
Unused allowance is lost on 5 April. You cannot carry £5,000 you did not use this year into next year. The government has said the overall £20,000 limit, the £4,000 Lifetime ISA limit and the £9,000 Junior ISA limit stay frozen until at least April 2030, so the 2027/28 allowance will also be £20,000.
If you want to see what the allowance is worth to you, our cash ISA vs savings calculator compares tax-free interest with an ordinary savings account at your tax rate, and our best cash ISA apps and best stocks and shares ISA apps list where to put it.
Frequently asked questions
What is the ISA allowance for 2026/27? £20,000 across all your adult ISAs between 6 April 2026 and 5 April 2027. Up to £4,000 of it can go into a Lifetime ISA. A Junior ISA has its own £9,000 limit per child.
Can I have two cash ISAs in the same tax year? Yes. Since 6 April 2024 you can pay into more than one cash ISA, or more than one stocks and shares ISA, in the same tax year, as long as the total across all of them stays within £20,000. Only the Lifetime ISA is limited to one a year.
Is the cash ISA limit still being cut to £12,000? No. The Budget on 28 October 2026 cancelled the cut, and HMRC has confirmed the £20,000 cash ISA limit stays from 6 April 2027.
Does transferring an ISA to a new app use up my allowance? No, as long as the new provider arranges the transfer. Withdrawing the money yourself and paying it into the new app counts as a fresh payment.
What happens if I pay in more than £20,000? Apps cannot see each other’s records, so the overpayment may go through. HMRC usually spots it from provider returns, and the excess is removed from the ISA with any tax relief on it taken back. Track your total yourself.
Does the Lifetime ISA bonus count toward my £20,000? No. Only the £4,000 you pay in counts. The government’s 25% bonus, up to £1,000 a year, sits on top.