Kroo Bank Review: 3.00% for a Year, Then 1.00%
Kroo bank review, Oct 2026: new accounts earn 3.00% AER for 12 months, then 1.00% at today's Bank Rate. Fees, overdraft and what the app cannot do.
This Kroo bank review starts with the number that changed on 5 October 2026. Kroo now pays new customers 3.00% AER variable on their current account balance, but 2.00 points of that is a bonus that ends after 12 months. What is left is a tracker set 2.75 points below the Bank of England base rate, which is 1.00% with Bank Rate at 3.75%. Customers who opened before 5 October keep an older tracker, 1.10 points below base, which pays 2.65% AER today.
So Kroo is still a good free current account to spend from and earn on, but for new customers it is a one-year deal, not a permanent home for savings. We read every figure below from Kroo’s own site and help centre on 20 October 2026.
Kroo at a glance
| What Kroo offers | |
|---|---|
| Interest, accounts opened from 5 Oct 2026 | 3.00% AER / 2.96% gross variable for 12 months (2.00% fixed bonus plus a tracker at base minus 2.75%) |
| Interest after the first year | Tracker at base minus 2.75%: 1.00% at today’s Bank Rate |
| Interest, accounts opened before 5 Oct 2026 | 2.65% AER / 2.62% gross variable (base minus 1.10%) |
| Balance that earns interest | Up to £500,000 |
| Interest paid | Calculated daily, paid on the 1st of each month |
| Monthly fee | None |
| Card spending and ATM withdrawals abroad | No Kroo fee, Visa exchange rate with no markup |
| Overdraft | 39.9% EAR/APR variable, invitation only |
| Cash ISA | Flexible Cash ISA, 3.00% AER variable |
| Personal loans | £1,000 to £25,000 over 1 to 5 years, representative 14.9% APR |
| Protection | Licensed UK bank, FSCS cover up to £120,000 per customer |
The interest rate, and the cliff after 12 months
The 3.00% has two parts. The 2.00% bonus is fixed for the first 12 months from the day you open the account. The other 1.00% is a tracker that moves with Bank Rate within two working days of any change. If the Bank cuts rates during your first year, your total falls with it; the 2.00% does not.
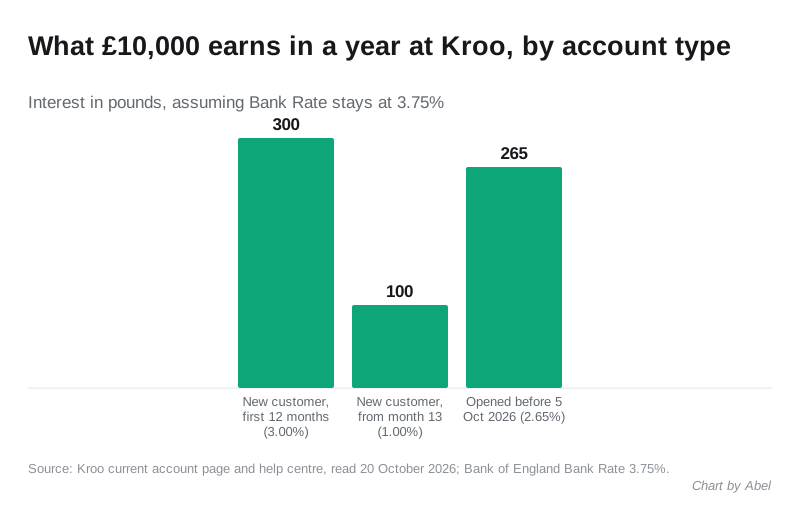
When the year ends, the bonus simply stops and the account carries on at the tracker. Kroo says it will warn you before that happens. Here is what £10,000 left in the account earns, assuming Bank Rate stays at 3.75%:
| Account | Rate | Interest on £10,000 for a year |
|---|---|---|
| New customer, first 12 months | 3.00% AER | about £300 |
| New customer, from month 13 | 1.00% | about £100 |
| Opened before 5 Oct 2026 | 2.65% AER | about £265 |
The bonus has no strings beyond being new. There is no minimum deposit, no monthly pay-in and no spending target. Interest is worked out on the end-of-day balance across the main account and your Pots together, so moving money into a Pot does not cost you anything.
Two things existing customers should know. You cannot close your account and reopen to get the bonus: Kroo excludes anyone who held an open account before midday on 5 October 2026, and a closed Kroo current account cannot be reopened. And your 2.65% is now the better long-term rate, so there is no reason to move.
Kroo’s Flexible Cash ISA
The Cash ISA pays 3.00% AER variable with no bonus element, so unlike the current account it does not drop after a year. It is flexible, meaning you can take money out and put it back in the same tax year without using up more allowance. You need a Kroo current account first, deposits are capped at £20,000 a tax year, and Kroo says it gives 14 days’ notice before cutting the rate.
That makes the ISA, not the current account, the better place for a new customer’s longer-term savings at Kroo. On ISA transfers in, Kroo accepts cash ISAs only and does not take partial transfers. From 6 April 2027 the cash ISA allowance falls to £12,000 for most savers; our page on the cash ISA limit cut explains who it affects, and moving an ISA between apps covers the transfer rules.
Fees: what costs nothing and what does
Kroo’s fee information document lists £0 for running the account, Direct Debits, standing orders, Faster Payments, card payments in pounds or foreign currency, and cash withdrawals at home or abroad. The charges are few:
- CHAPS payment: £20.
- Card replacements: the first is free; the second and later ones in a 12-month period cost £5, and delivery outside the UK costs £10.
- ATM operators abroad can add their own fee, which Kroo does not control.
Abroad, Kroo passes on Visa’s exchange rate without a markup. That puts it in the same group as the fee-free travel cards in our best bank account for travelling roundup, with one gap covered below: you cannot send or receive money internationally.
The overdraft
Kroo’s overdraft charges 39.9% EAR/APR variable, arranged or unarranged, and the rate is the same whatever your age. Kroo’s own example: a £1,200 arranged overdraft used for 30 days costs £22.13. Its fee information document, dated April 2025, also says it will not charge more than £15 interest in any month, which does not square with that example, so check the figure in the app before you rely on either.
You cannot apply on demand. Overdrafts are by invitation only, sent by app and email to customers Kroo picks, and support staff cannot invite you manually. One useful rule: if you go overdrawn while you have money sitting in Pots that would cover it, Kroo does not charge interest.
What Kroo cannot do
This is where Kroo falls behind Monzo and Starling, and it decides whether it can be your only bank:
- No international payments. You cannot send money abroad or receive payments from outside the UK, and there is no IBAN.
- No cash or cheque deposits.
- Sole accounts only. No joint, children’s, business or separate savings accounts.
- No full Current Account Switch Service. Kroo is not a CASS member. It accepts a switch mandate with a switch date at least 20 working days away, but it says moving your Direct Debits yourself is quicker. That also rules Kroo out of most bank switching offers, which require a full CASS switch.
- No overdraft on request, as above.
You need to be 18 or over and a UK resident, and Kroo runs a credit check through TransUnion and a fraud check through CIFAS when you apply.
Is your money safe with Kroo?
Yes, to the same standard as any high street bank. Kroo Bank Ltd is authorised by the Prudential Regulation Authority and regulated by the FCA and PRA (firm reference 953772). Eligible deposits are covered by the Financial Services Compensation Scheme up to £120,000 per customer. That limit covers your current account, Pots and Cash ISA together, not each one separately. Our savings pot vs savings account page explains how the limit adds up when you split money between products.
How it compares
Against Monzo, Kroo pays more in year one, and it pays it on the spending balance itself, where Monzo pays its interest through separate savings pots. After the bonus ends, a free Monzo Instant Access pot (2.75% when we checked on 17 October) beats Kroo’s 1.00% tracker comfortably; our Monzo savings pot rates page has the full table. Starling and Monzo both handle international transfers, joint accounts and cash deposits, which Kroo does not.
Should you open a Kroo account?
Open one if you want a fee-free spending card for travel and somewhere to park money that earns 3.00% for a year without any conditions. Treat the first anniversary as a deadline: move savings into Kroo’s ISA or another easy-access account before the rate drops to the tracker.
Skip it as a main account if you receive money from abroad, pay in cash, want a joint account, or need an overdraft you can count on. And if you already have a pre-October account at 2.65%, keep it.
You can check the live rate on Kroo’s interest rate help page.
Frequently asked questions
What interest rate does Kroo pay in October 2026? New customers who open an account from midday on 5 October 2026 get 3.00% AER variable for 12 months. Accounts opened before that date earn 2.65% AER variable. Both apply to balances up to £500,000.
What happens to the Kroo rate after 12 months? The 2.00% fixed bonus ends and the account earns the tracker rate, set 2.75 points below Bank Rate. With Bank Rate at 3.75% that is 1.00%. Kroo notifies you before the bonus finishes.
Is Kroo a real bank? Yes. Kroo Bank Ltd is authorised by the Prudential Regulation Authority and regulated by the FCA and PRA, and eligible deposits are protected by the FSCS up to £120,000 per customer.
Can I get the new Kroo rate by closing and reopening my account? No. Anyone who held an open Kroo account before midday on 5 October 2026 is excluded from the bonus, and a closed Kroo current account cannot be reopened.
Does Kroo charge fees abroad? Kroo charges nothing for card payments or cash withdrawals abroad and uses Visa’s exchange rate without a markup. The ATM operator may add its own fee.
Can I send money abroad with Kroo? No. Kroo does not support sending international payments or receiving money from outside the UK, and its accounts have no IBAN.