Vanguard UK Review: £4 a Month Under £32k, 0.15% Above
Vanguard UK charges £4 a month below £32,000, then 0.15% capped at £375. Who that suits, what the app can and cannot do, and how drawdown works.
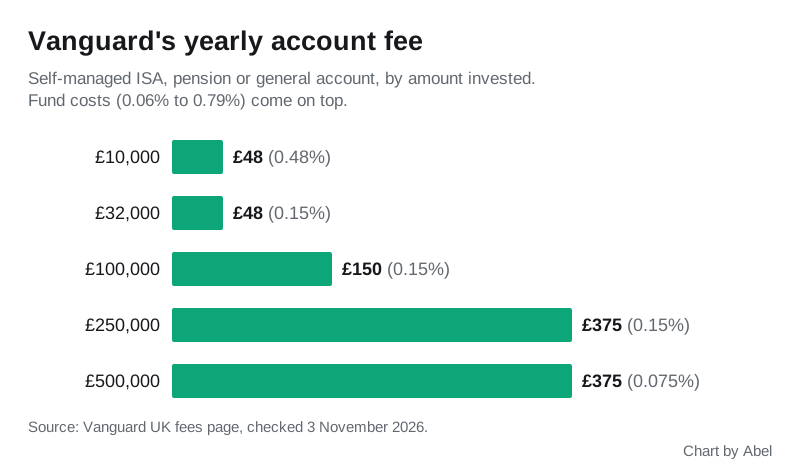
This Vanguard UK review turns on one threshold: £32,000. Below it, Vanguard charges a flat £4 a month (£48 a year) to hold a self-managed Stocks and Shares ISA, pension or general account. At £32,000 and above, the fee becomes 0.15% a year of what you have invested, and it stops rising at £375 however large your balance gets.
That makes Vanguard one of the cheapest homes for a big pot of index funds, and one of the dearer ones for a small pot. The other catch is choice: you can only buy Vanguard’s own funds and ETFs.
Every figure below was checked on Vanguard’s own UK fees, app, account-opening and help pages on 3 November 2026.
Vanguard UK at a glance
| What you pay or get | |
|---|---|
| Account fee, under £32,000 invested | £4 a month (£48 a year) |
| Account fee, £32,000 and over | 0.15% a year, capped at £375 |
| Fund running costs | 0.06% to 0.79% a year, depending on the fund |
| ETF buying and selling costs | Spread of 0.01% to 0.26%; optional quote-and-deal service £7.50 a trade |
| Minimum to start | £500 single payment, or a monthly payment (£100 a month on the Junior ISA) |
| Interest on cash | 1.85% (Vanguard keeps anything it earns above that) |
| Accounts | Stocks and Shares ISA, Junior ISA, Personal Pension (SIPP), general account, plus managed versions |
| Investments | Vanguard funds and ETFs only |
| Fees not charged | Transfers out, switching funds, withdrawals, closing your account |
What Vanguard actually charges
The account fee is charged only on money that is invested, not on cash sitting in the account. It is worked out across all your Vanguard accounts together, so an ISA and a pension count as one balance for the £32,000 test and share one £375 cap. The fee is collected every three months from the date you opened the account, by Direct Debit or from cash in the account. If neither covers it, Vanguard sells units from your largest fund to pay it.
The £4 minimum took effect on 28 February 2025. Before that, a small ISA paid 0.15% like everyone else, so £5,000 cost £7.50 a year. It now costs £48. That change is the main reason Vanguard has dropped down the rankings for beginners.
Put the two fees side by side and the shape is clear:
- £10,000 invested: £48 a year, which is 0.48% of your money.
- £32,000: £48, the point where the flat fee and 0.15% meet.
- £100,000: £150.
- £250,000: £375, the cap.
- £500,000: still £375, which works out at 0.075%.
On top of that you pay the running cost of each fund. A global tracker such as FTSE Global All Cap sits towards the cheap end of Vanguard’s 0.06% to 0.79% range; active funds sit higher. There is no dealing charge on funds, and ETF trades carry only the market spread unless you choose the £7.50 quote-and-deal service for a live price.
Who the fee suits, and who it does not
Vanguard is good value from roughly £32,000 upwards, and very good value past £250,000, where the fee is frozen. Someone with £400,000 across an ISA and a SIPP pays £375 a year to Vanguard; a percentage-fee platform charging 0.25% would take £1,000.
Below £32,000 the flat £48 looks expensive next to apps that charge nothing to hold ETFs. Our InvestEngine review covers the closest free alternative: no account fee on a DIY ETF portfolio, in an ISA or a SIPP, and Vanguard’s own ETFs are on its list. Someone with £8,000 who only wants a Vanguard tracker can hold the same fund there for nothing beyond the fund cost. Trading 212 and Lightyear also charge no account fee.
The Junior ISA is the exception to the £4 rule. Vanguard does not apply the minimum to Junior ISAs, so they pay 0.15% (capped) from the first pound. That keeps Vanguard competitive for children’s accounts; see our best Junior ISA apps for the comparison.
The Vanguard app: what it does now
Vanguard does have an app, on the App Store and Google Play, but it is a companion to the website rather than a full replacement. You cannot open an account in it: Vanguard says you can only do that on its website.
Once you have an account, the app lets you:
- log in with fingerprint or face ID;
- see your balance, account details and transactions;
- buy and sell funds;
- set up a monthly payment, or invest again in a fund you already hold;
- check whether a transfer to Vanguard is in progress, done or cancelled;
- withdraw cash from your Stocks and Shares ISA or general account.
In Vanguard’s own words, there is “no live ETF trading just yet”. If you build your portfolio from ETFs rather than funds, you will be using the website. Pension withdrawals are also website-only, for a reason covered below.
The pension and drawdown
Vanguard’s Personal Pension is a SIPP restricted to Vanguard funds, on the same account fee. It runs all the way through retirement, which many cheap apps do not. From 55 (rising to 57 in 2028) you can take flexible income (drawdown), individual lump sums (UFPLS) or use the pot to buy an annuity, and Vanguard lists no separate charge for withdrawals.
Taking tax-free cash for the first time is not instant. Vanguard requires a phone appointment with one of its retirement consultants, which can take up to six working days to book in busy periods, and the whole withdrawal usually takes around three weeks. The consultant gives guidance, not regulated advice. Vanguard does not offer capped drawdown and will not accept a transfer of a pension already in capped drawdown.
Our best SIPP apps page sets Vanguard’s pension against Freetrade, InvestEngine, AJ Bell, Moneybox and PensionBee on £20,000, £50,000 and £150,000 pots.
Interest on cash
Uninvested cash earns 1.85%, a “managed rate” that Vanguard sets and reviews. Vanguard’s own table shows it falling from 2.45% in August 2024 to 1.85% from 18 December 2025, and Vanguard keeps any interest it earns above the rate it pays you. Cash is not charged the account fee, but 1.85% is well below what an easy-access savings account pays, so do not park money here for long. Our emergency fund page covers better homes for cash.
Is Vanguard safe?
Vanguard Investments UK is authorised and regulated by the Financial Conduct Authority. Your investments are held separately from Vanguard’s own money, and eligible claims are covered by the Financial Services Compensation Scheme if the firm fails. The FSCS investment protection page explains the limits. None of that protects you from the value of your funds falling: investments can go down as well as up.
The limits
- Vanguard products only. No individual shares, no iShares or HSBC trackers, no investment trusts.
- No Lifetime ISA. For a first home or a bonus on retirement saving, see best Lifetime ISA apps.
- Regular payments come from your bank only. You cannot set a regular investment to sweep up cash already in the account; Vanguard says you invest that by hand, at no cost.
- The app trails the website, with no account opening, no live ETF dealing and no pension withdrawals.
Our verdict
Vanguard UK is a strong choice once you have £32,000 or more to invest in index funds and want one provider for an ISA, a pension and drawdown later on, with a fee that stops at £375. Under £32,000 the flat £48 makes it hard to recommend over a free ETF app holding the same Vanguard trackers, unless the account is a Junior ISA. If you are just starting, read how to start investing with an app first, then compare the best stocks and shares ISA apps.
Frequently asked questions
How much does Vanguard UK charge? £4 a month (£48 a year) if your total invested balance is under £32,000, then 0.15% a year capped at £375. Fund costs of 0.06% to 0.79% come on top.
Does the £4 Vanguard fee apply to a Junior ISA? No. The £4 minimum applies only to self-managed ISAs, pensions and general accounts. Junior ISAs, and Vanguard’s managed accounts, pay 0.15% a year, capped at £375.
What is the minimum investment at Vanguard? You can start with a single payment of £500 or set up a monthly payment; the Junior ISA page puts the monthly minimum at £100. ISA and pension transfers in have no minimum.
Can I open a Vanguard account in the app? No. Vanguard says accounts can only be opened on its website. The app is for managing an account you already have.
Can I buy ETFs in the Vanguard app? Not yet. Vanguard’s app page says there is no live ETF trading in the app just yet; you can buy and sell funds, and use the website for ETFs.
Is Vanguard good for a SIPP? For larger pots, yes: the fee caps at £375 and drawdown is supported with no separate withdrawal charge. Below £32,000, a free SIPP such as InvestEngine’s costs less if you are happy with ETFs only.